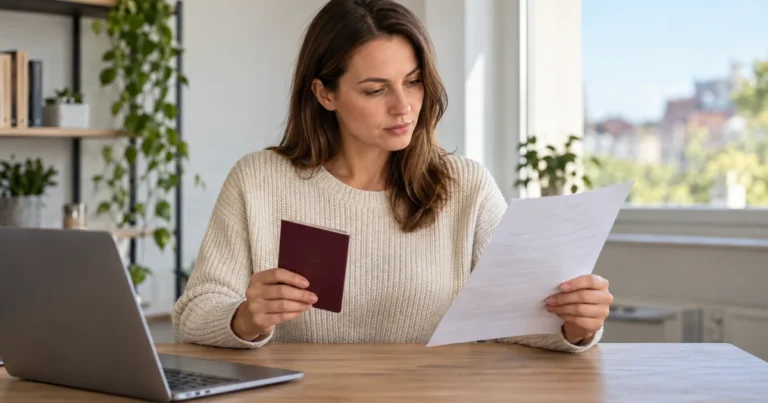
Choosing insurance for a Polish national visa application is not just a matter of finding a policy and paying for it. The document should fit the planned stay, identify the insured person correctly and be available in a form that can be added to the application. Before buying, compare the exact travel dates, the correct geographical area, the insured person’s full legal name and whether the seller can issue a document you can save. Requirements and document-handling practices can change, so verify the current instructions for your place of application. Insurance supports the application, but it does not guarantee that a visa will be issued.
What the policy needs to match
Start with the application, not with a list of optional extras. Write down the planned arrival date, departure date, destination and the personal details shown in the applicant’s travel document. Then compare those facts with the policy proposal and the document that will be issued after purchase.
The main checks are simple:
Do not assume that a product described as “visa insurance” automatically matches every national visa case. A national visa, a short-stay Schengen visa and a residence-permit procedure are different purposes. If you are still deciding which route fits your situation, compare the dedicated information on insurance for a Polish national D visa, medical insurance for a Schengen visa and medical insurance for a temporary residence permit.
Check current consular instructions before purchase and before submitting the application.
How to check dates and territory
Match the period to the planned stay
Check the first and last day shown on the proposal before you pay. A small typing error can leave the policy document inconsistent with the itinerary or application. Look at the dates as calendar dates rather than relying on a displayed number of days. If the journey changes, ask what must be done to adjust the policy; do not assume that a change happens automatically.
Also distinguish between the purchase date, the policy issue date and the period of protection. They may appear near one another on a document but do not necessarily describe the same thing. The useful question is straightforward: on what date and at what time does protection begin, and when does it end under the current terms?
Read the territorial wording, not only the product name
Treat territory as a policy field that needs its own check. “Poland,” “Schengen” and broader European wording are not interchangeable. The correct choice depends on the planned journey and the current requirements applicable to the application.
A concrete example shows why the wording matters. Under the 2026 Compensa Cudzoziemiec terms, the medical-cost clause applies only if the customer has selected this clause. That clause concerns illness or the consequences of an accident occurring in Poland and medically necessary treatment that must be undertaken immediately during the stay. In other words, this wording supports cover in Poland only for that clause; it does not prove that every policy automatically covers the entire Schengen area.
If the itinerary includes travel beyond Poland, check the selected policy’s territorial entry rather than extending the Polish scope by assumption. Coverage and visa validity are separate questions: a policy can only be assessed against its own wording, while the authority assesses the application under its current rules.
Insured-person details and the certificate
Check every personal field
Copy names exactly as they appear in the applicant’s travel document. Review the order and spelling of given names and surname, date of birth and any other identifier requested during purchase. Do this before payment and once more when the document is issued.
If another person buys the insurance, confirm that the proposal clearly distinguishes the buyer from the insured person. The person who pays is not automatically the person whose medical costs are insured. The document intended for the application should identify the correct insured person without requiring the reader to infer this from payment details.
Make sure the document will be accessible
Confirm the certificate format before purchase. Check whether the process provides a downloadable policy or certificate, what language or languages appear on it, and whether the file shows the insured person, period and territory clearly. Do not assume that every seller provides the same document immediately or that every document will be accepted without further checks.
Save the final file rather than relying only on an email link. Review it while there is still time to report an error. If you are unsure whether an additional language version is needed, read the guide on whether a policy needs translation and verify the current instruction for your application.
Keep policy and payment records together in a folder that you can access during the application process and the insured stay. This is practical record-keeping, not a claim that every authority asks for the same set of files.
What to read before purchase
A certificate is only a summary of the contract. Read the current policy terms and the proposal together. Focus on the medical-cost clause for sudden illness or accident, the territorial scope, the protection period, exclusions, assistance instructions, claim procedure and the documents that may be requested after an insured event.
Avoid transferring one insurer’s procedure to another insurer or even to a newer version of the same product. For example, the 2020 Uniqa KLC terms provide a product-specific example of claim documentation. They say a claim notice should include the policy number, a detailed description of the event, a medical opinion containing the diagnosis and recommended treatment, and supporting invoices, bills, hospital certificates and proof of payment. This dated example is useful as a reminder to preserve records, but it is not a universal checklist for every policy. Follow the instructions in the terms that apply to the policy you actually buy.
Before accepting an offer, ask yourself:
Current terms take priority over general descriptions. If the proposal, certificate and terms appear inconsistent, resolve the difference before paying rather than guessing which wording will control.
When the details match your planned stay and application, buy your insurance using our English-language form:
Buying a policy does not guarantee a positive visa decision. It gives you a contract whose dates, territory, insured person and documented scope should be checked before it is used in an application.
Frequently asked questions
Does insurance guarantee that I will receive a Polish national visa?
No. Insurance is one element of an application, and purchasing it does not guarantee visa issuance. The competent authority evaluates the application. Check the current instructions for your place of application and make sure the insurance document matches the information you submit.
Is every policy described as visa insurance valid throughout the Schengen area?
Do not assume so. Read the territorial field in the proposal, certificate and current terms. If your itinerary extends beyond Poland, verify that the selected territory fits both the journey and the current application requirements.
Should the policy cover the exact dates of my stay?
Compare the beginning and end of protection with the planned stay and the current instructions applicable to your application. Check the actual calendar dates on the issued document; do not rely only on a duration shown in days.
What personal details should I check on the document?
Check the insured person’s name against the travel document, along with the date of birth and any other identifier collected during purchase. If someone else pays, confirm that the buyer and insured person are shown in their proper roles.
Do I need a translated insurance document?
That depends on the document you receive and the current instructions for the application. Do not assume that one rule applies everywhere. Verify the required language and, if needed, review our guidance on policy translation before submitting the file.
What should I keep if I need to report an insured event?
Follow the current terms for your own policy. As a practical measure, retain the policy number, a clear account of what happened, medical documentation and financial records connected with the event. The exact required set can differ by insurer, product and version.
Final checklist before you pay
Pause on the final screen and compare the proposal with your travel document and planned stay. Confirm the insured person, protection dates and territory. Check that the relevant medical-cost scope is selected, read the exclusions and claim instructions, and make sure you will receive a policy or certificate that can be saved.
Buy only after the checks are complete. Then review the issued document immediately and keep it with your application records. Finally, verify the current consular requirements before submission. That sequence reduces avoidable inconsistencies without making promises about how the authority will decide the visa application.


 English
 Polish
 Ukrainian
 Spanish
 Russian
 Turkish
 Indonesian
 Vietnamese